$100m Acquisition as First Deal
Former auto mechanic Eugene Polevoy is an independent sponsor based in Toronto. His strong opinions routinely go viral on LinkedIn and were recently featured in PitchBook's daily newsletter. Eugene walks through how he built and exited an HVAC platform and talks about his latest move into a $100m commercial generator services deal.

$100m Acquisition as First Deal
Former auto mechanic Eugene Polevoy is an independent sponsor based in Toronto. His strong opinions routinely go viral on LinkedIn and were recently featured in Pitchbook's daily newsletter. Eugene walks through how he built and exited an HVAC platform and talks about his latest move into a $100m commercial generator services deal.
Minds Capital is an equity fund for independent sponsors. We invest $1-3m of equity per platform and average one commitment per month.
This episode is sponsored by


After a law degree and 6 years in instutitonal PE at OnCap, Eugene saw that institutional capital often misses opportunities in the lower-middle market. As an offspring, he launched Frontier Service Partners by acquiring three HVAC branches with $7m of EBITDA, then grew that to $12.5m through operational improvements before exiting in 2024.
His most recent deal, which he counts as his first stand-alone, is a platform in the commercial generator services space, acquired at over $100m EV. This was sourced through a long-standing relationship and funded with the help of a well-connected, credential'd partner.
Eugene walks us through the contrasts between the Canadian and US M&A markets. He says Canada is bifurcated, where businesses are either too small or already institutionalized. In the US, there is deeper buyer demand and more openness to proprietary, relationship-driven deals.
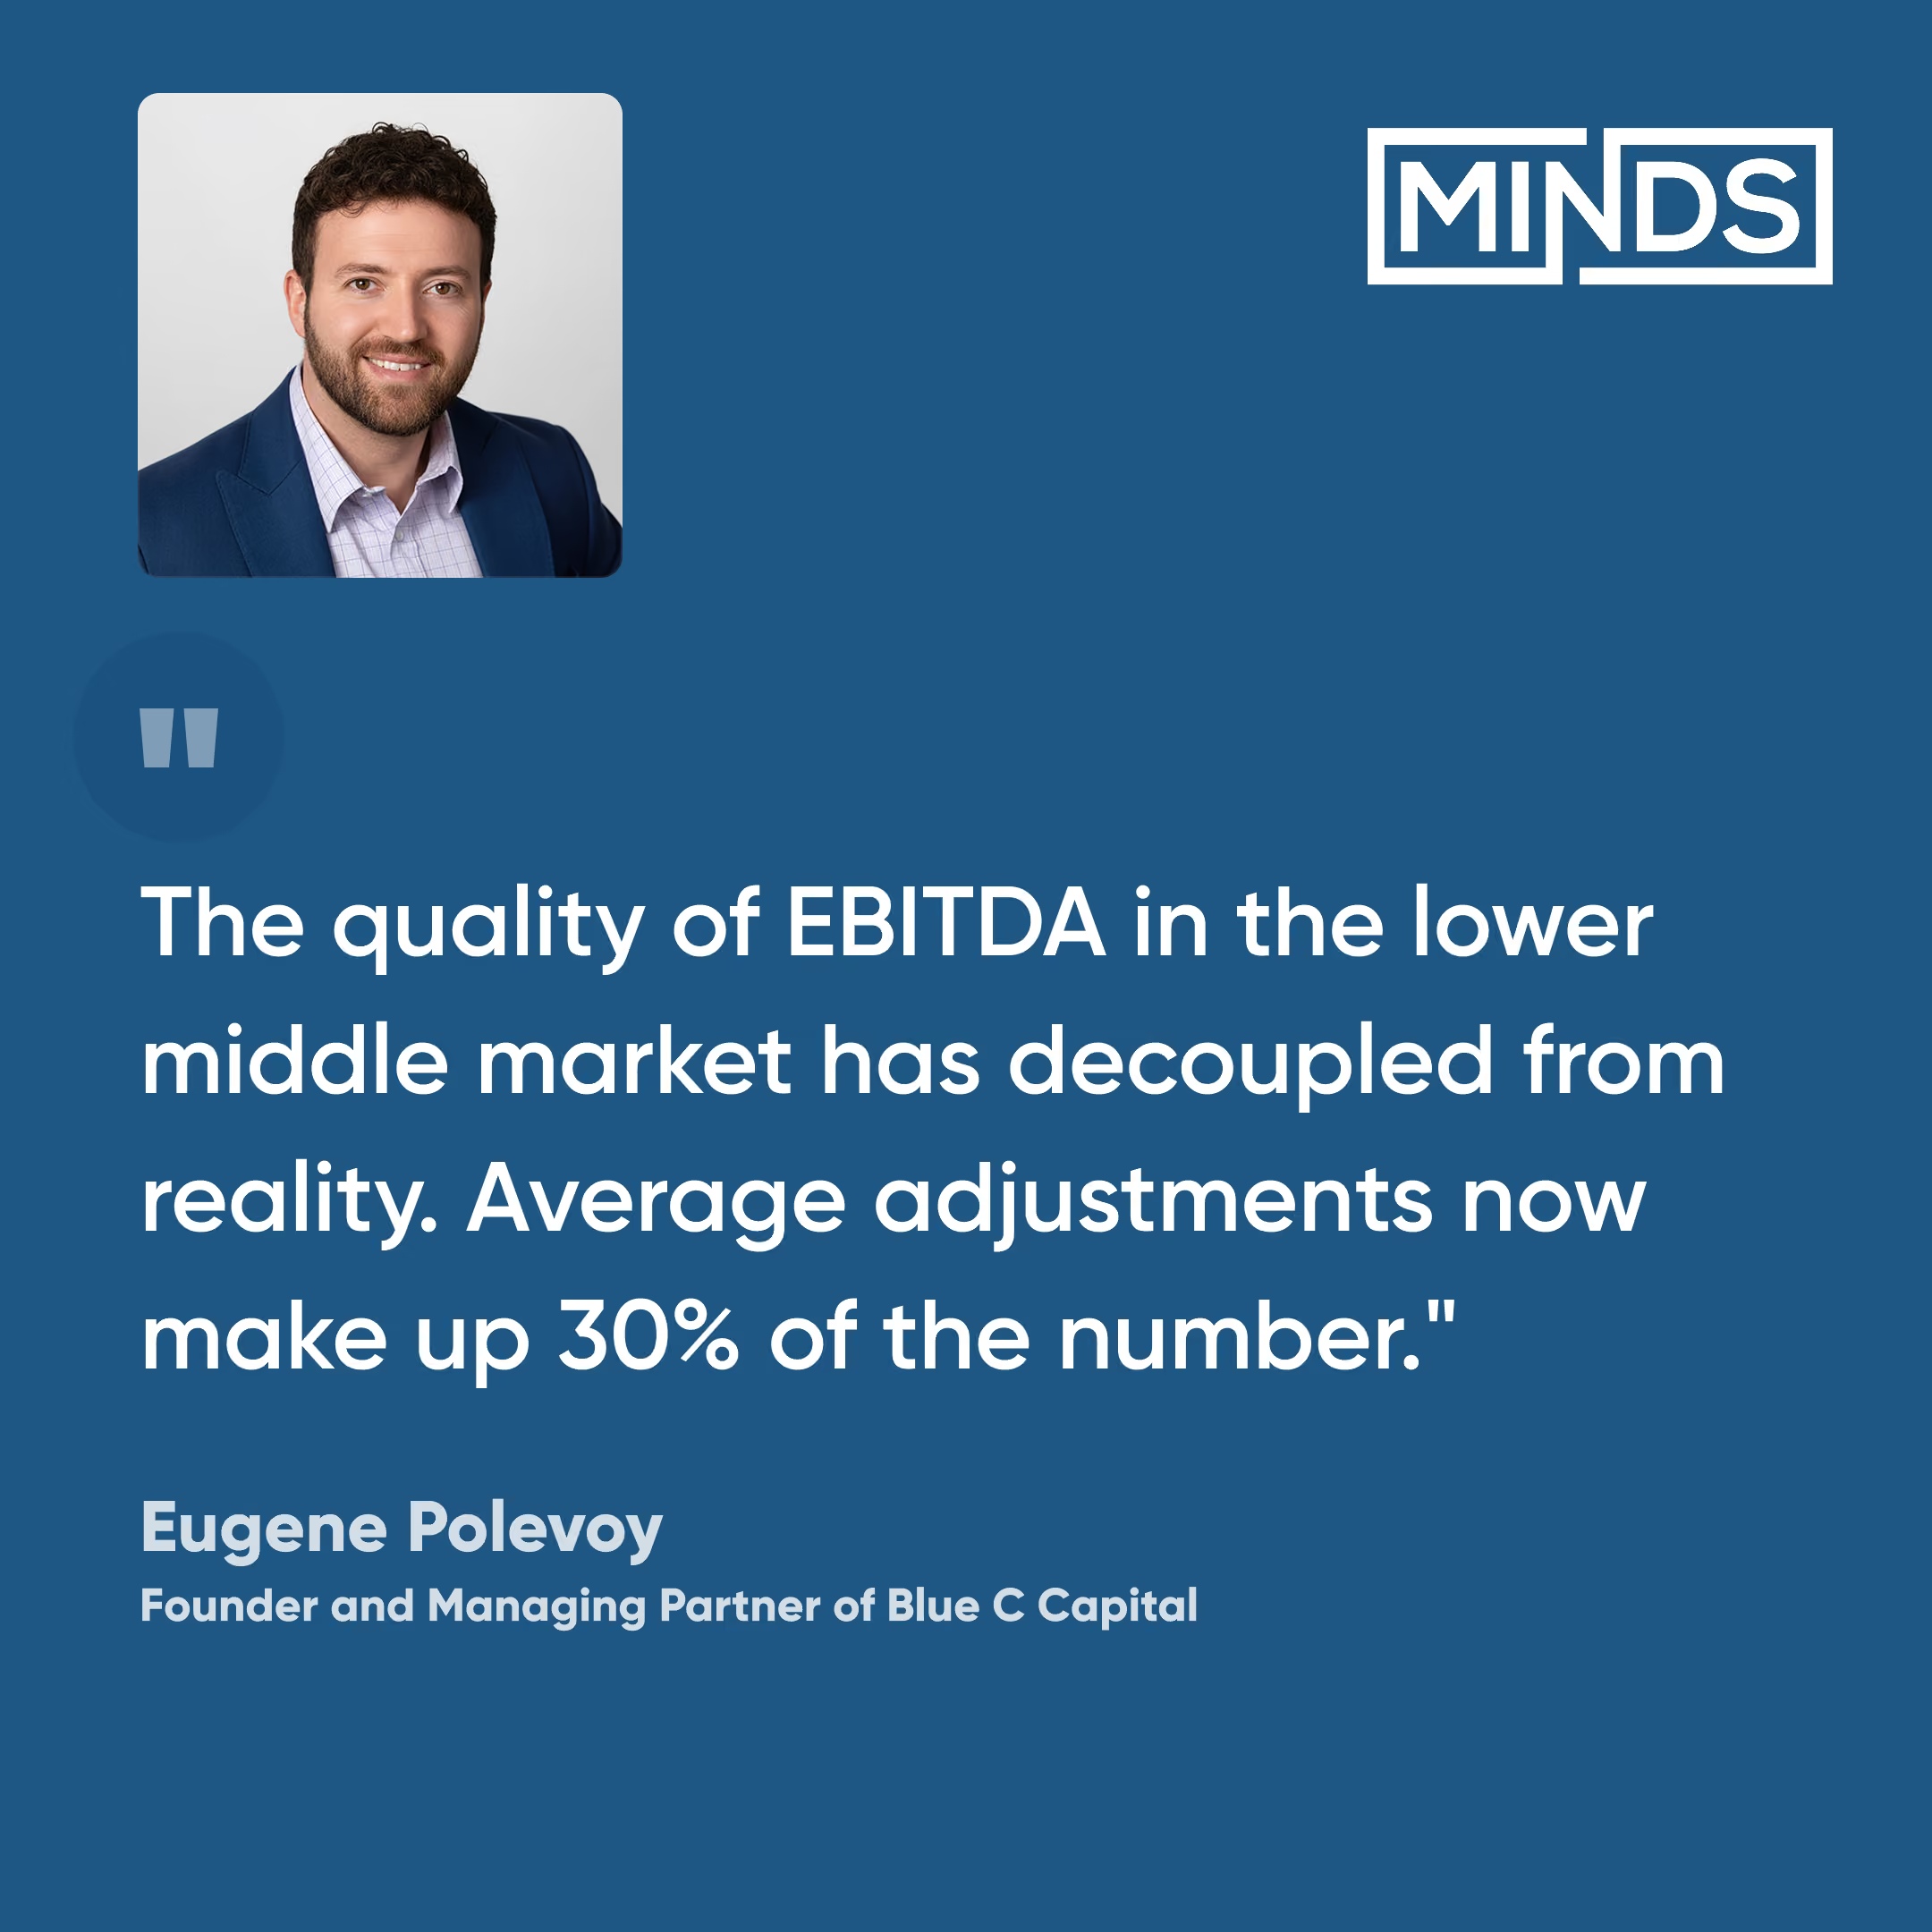
Eugene calls BS on EBITDA adjustments. He questions people's incentives, and challenges the integrity of nefarious QoE providers. He says add-backs have expanded meaningfully, particularly post-COVID, and warns that reported EBITDA sometimes overstates true cash flow. When leverage is underwritten against that number, the result is a capital structure that does not hold, leading to weaker returns and higher default risk. He says everyone in PE is aware, but no one dares say it out loud - until now, in this episode.
More recent episodes
32x MOIC After 100 Investors Said No
Since Kevin Ramsier's last appearance on this podcast, his firm, Sier Capital, has closed a new infrastructure platform (where Minds Capital is an investor) and exited another business that generated a 32x MOIC over a 7-year hold. The same business started with 95% customer concentration and nearly 100 investors said no.
The $600M Bet on Independent Sponsors
Grant Kornman co-founded NCK Capital as an independent sponsor in 2013, then moved to the capital side with Align Collaborate in 2023. Align now manages $600m+ across 2 dedicated funds and writes $10-40m equity checks into sponsor-led LMM deals. Grant has watched the independent sponsor market evolve from both sides.
815 Independent Sponsor Deals Analyzed
Greg Brown is a Professor of Finance at UNC Kenan-Flagler and Founder of the Institute for Private Capital. On July 15, 2026, he published the first large-scale study of independent sponsor performance, covering 815 deals. Investor-reported transactions generated a 2.86x average gross TVPI and 29.3% gross IRR, outperforming matched non-IS PE deals by 0.73x TVPI and 11.4% IRR on average, with no statistically significant increase in downside risk.