Robert Graham: 33 PortCos in 6 Years | SIG Partners
Robert Graham built 33 portfolio companies in 6 years through SIG Partners, starting with a healthcare platform that grew to $30M EBITDA.
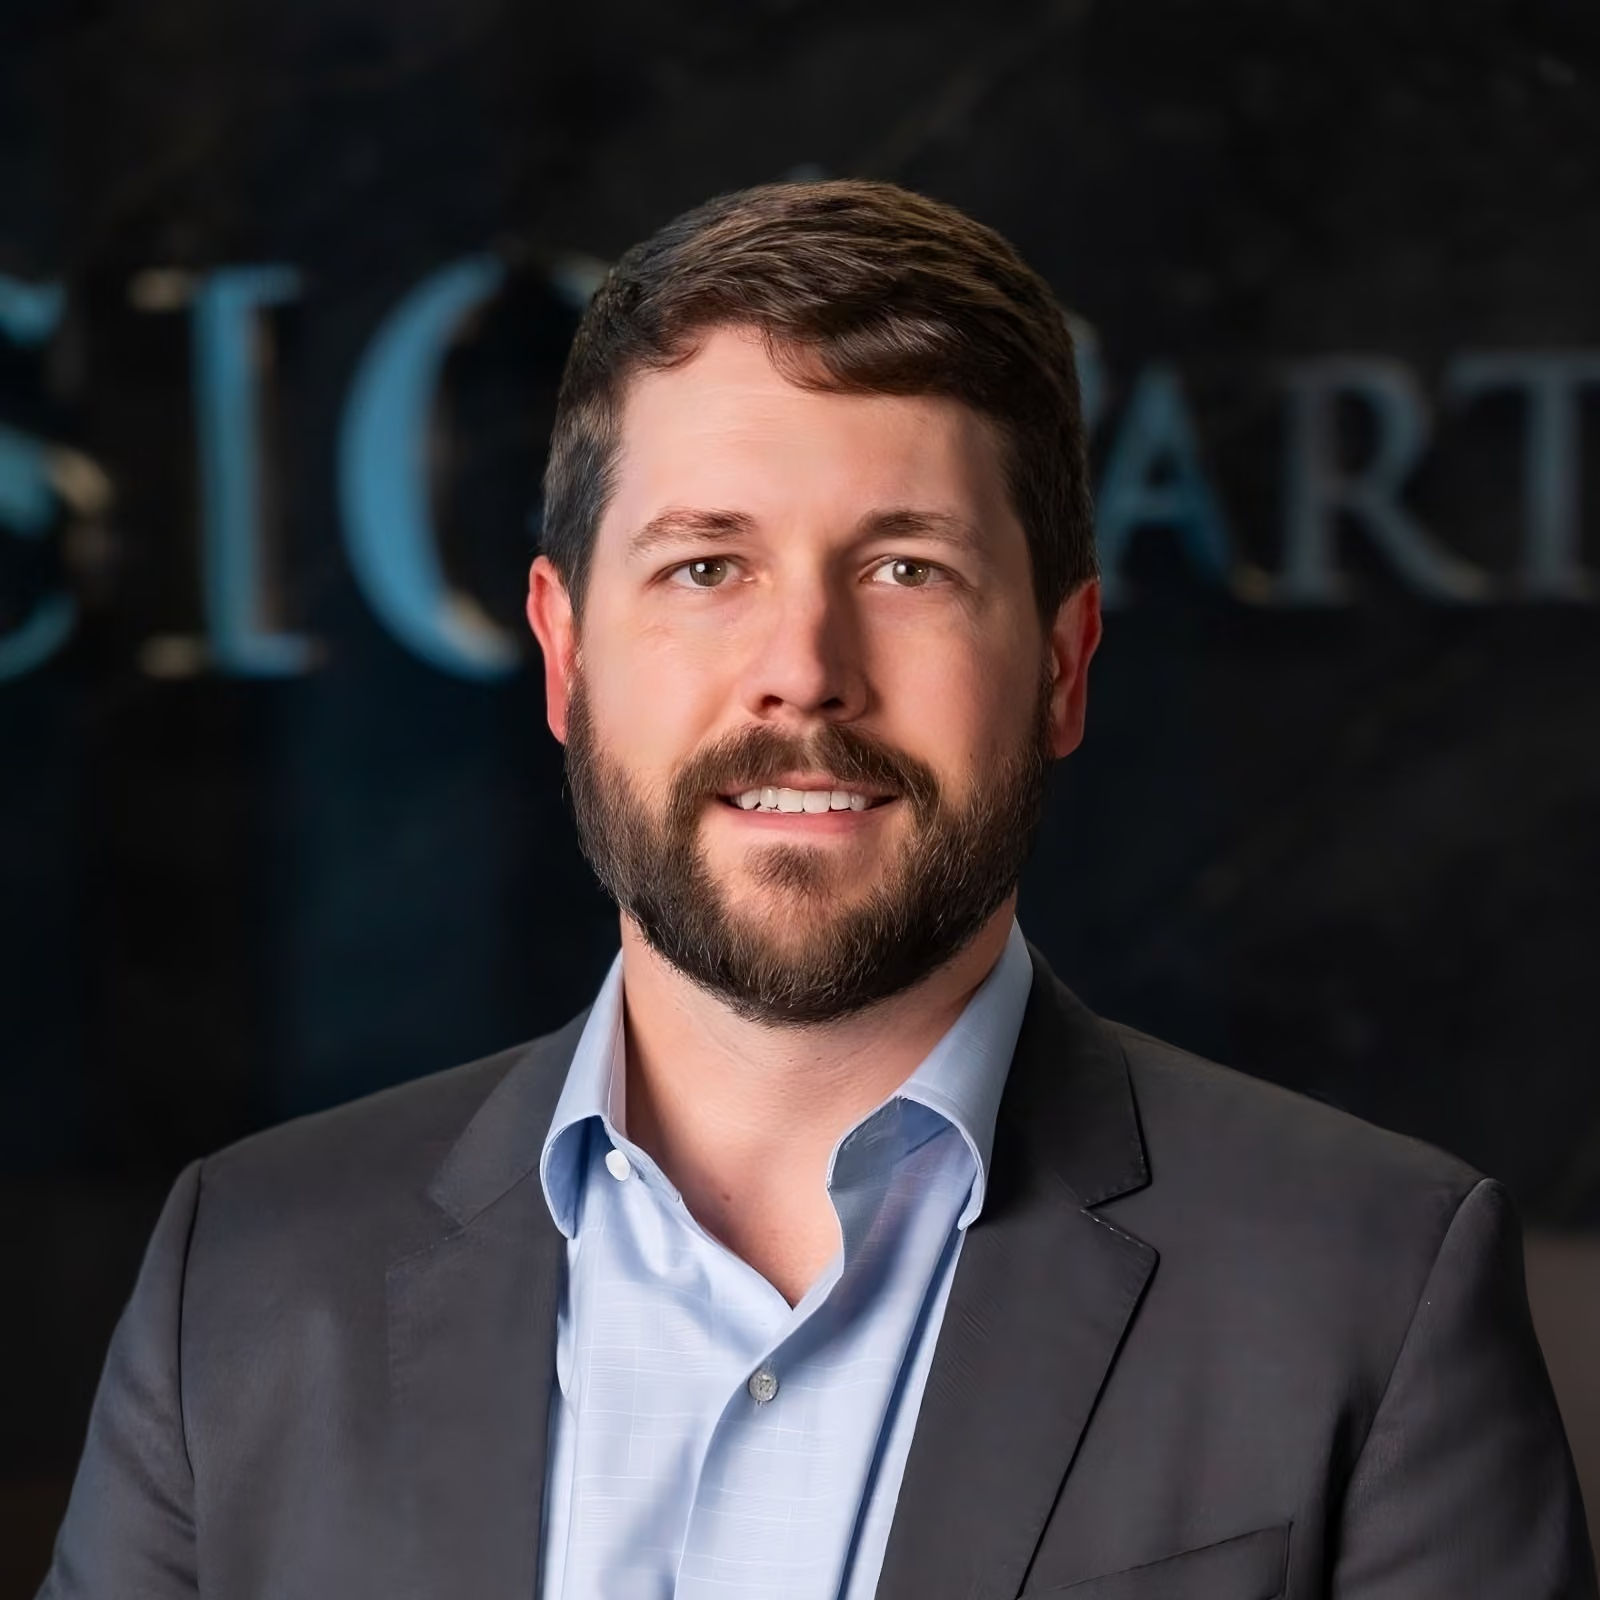

Robert serves as CEO of Pillar Health Group and is a Founding Partner at SIG Partners, operating out of the Old Parkland campus in Dallas. SIG has built a sizable presence online, approaching 10,000 followers on LinkedIn. They're well connected with SBA7a lenders, HNWis, brokers & intermediaries, and specialist vendors, giving him leverage across financing, execution, and repeatable deal flow. Years of consistency have produced durable relationships with SBA7a lenders, HNW investors, brokers & intermediaries, and specialist vendors who trust SIG's ability to close.

Pillar Health Group began with 3 small home-care, home-health, and hospice acquisitions in 2019. The early period was turbulent, but the business soon entered a breakout phase, ending 2024 at roughly $19m of adjusted EBITDA on close to $80m of revenue. Projections point toward nearly $30m of EBITDA in 2026, supported by ~$127m of revenue. About 40% of all growth has been organic, while the remainder has come through acquisitions. The organic push has centered on expanding scale and revenue, not tightening costs, drive pricing, or extracting efficiencies.

SIG Partners mirrors these principles. The firm employs a 5-person sourcing team and a dedicated post-closing growth leader. Pricing is a major lever across most SIG companies, and the firm deliberately favors "boring" businesses with stable demand and commercial headroom. The average acquisition is ~$2.5m of EBITDA; SIG closed nine such deals in 2024. Execution frameworks include EOS and double-the-business strategy planning. SIG has shifted from supporting first-time searchers to pairing mid-career operators with high-quality platforms, targeting a portfolio-level return near 30% IRR.

Robert argues forcefully for the value of SBA-enabled liquidity in the American small-business ecosystem. Default rates remain low (~3%), and he claims borrowers can reset their financial lives through well-structured bankruptcy protections. Leverage, liquidity, and second-chance mechanisms are far more constrained in Europe, which Robert uses to explain that the US better enables entrepreneurship, continuity of ownership, and the transfer of long-standing businesses to capable new stewards.
More recent episodes
Funding Deal #2 From Exit #1
Ben Tiggelaar acquired Enable Dental in 2017, ran it for five years and exited in 2022. He later bought Datatel with his own capital, growing it from a $6m revenue MSP with 55–60% recurring revenue to ~$8m with ~90% recurring revenue.
Rolling Up Tiny $400k EBITDA Targets
Ziv Bendor co-founded Pinewell Capital in Scottsdale in 2016. Pinewell is now on its 5th platform and 10th acquisition across B2B and B2C businesses, including one strategy that combined four sub-$500k EBITDA companies into a ~$7m EBITDA platform.
Over $60m of Second Bite Liquidity
Chad Scripps started Black Lake Capital in 2013 after stints at McKinsey, HIG, and several hedge funds. Based in Denver, Black Lake closes just 1-2 acquisitions per year despite reviewing thousands of opportunities. The firm calls itself tech-enabled, but Chad admits that’s a loose moniker: “If you’ve got email, we’ll call you tech enabled.”