7x Organic EBITDA Growth After Liberating Employees
Rise Run Capital's Corbin Cook and Alex Swanston discuss their independent sponsor success: 5 platforms, $50m+ EBITDA, and a 7x exit in 4 years.
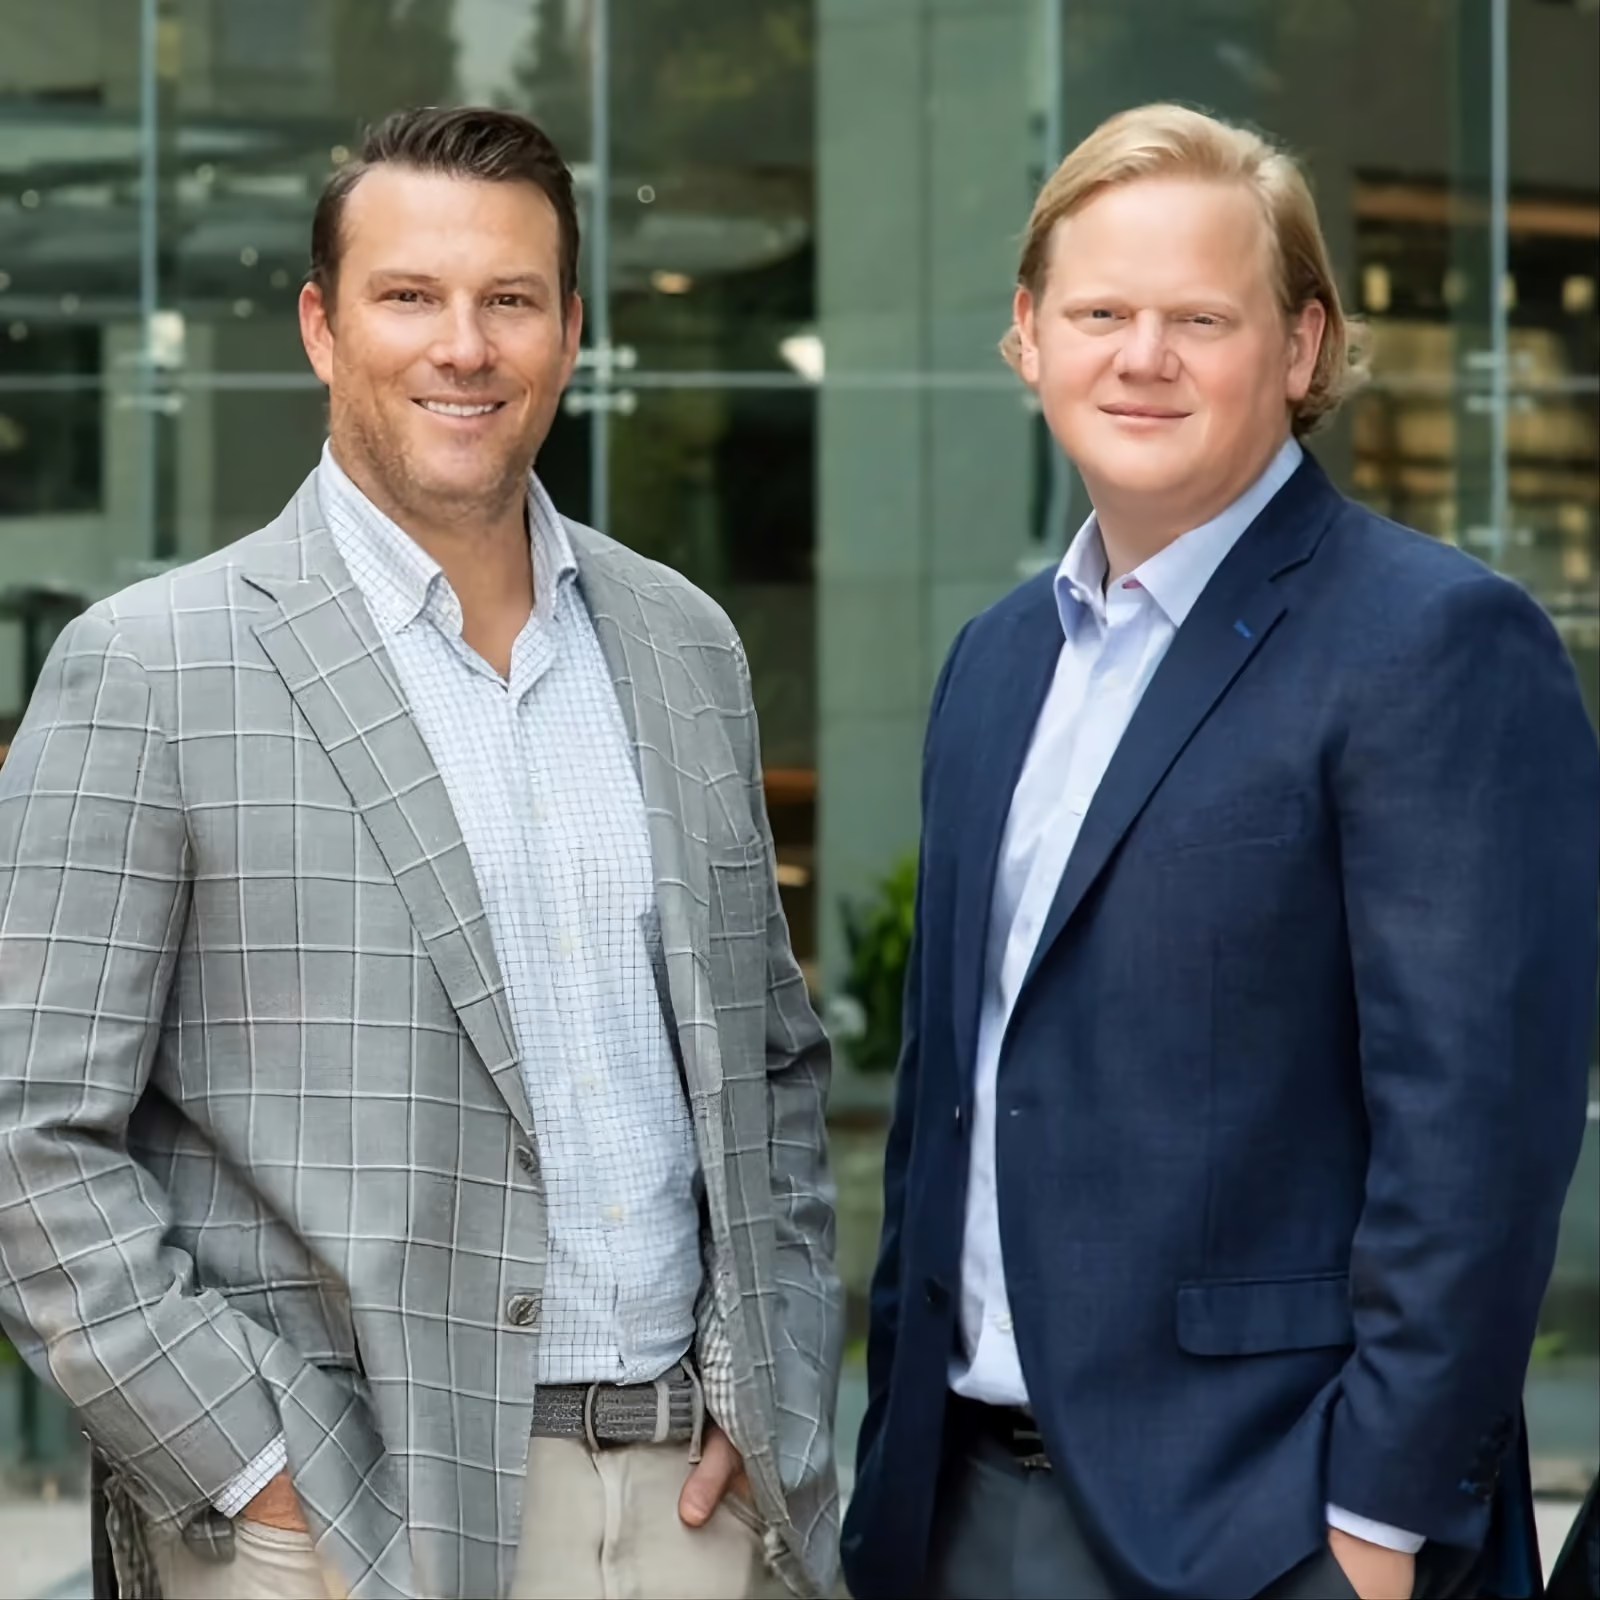

Corbin Cook and Alex Swanston of Rise Run Capital challenge the "get rich slow" reputation of independent sponsorship. Since starting 6 years ago, after having roadmapped their firm over beers by a bonfire in Wyoming, they have acquired 5 platforms, reaching more than $50m of aggregate EBITDA, before landing their 1st home run exit (7x EBITDA growth in 4 years) a few months ago.
Minds Capital is an equity fund for independent sponsors. We invest $1-3m of equity per platform and average one commitment per month.
This episode is sponsored by
The Dallas-based firm has a team of 6, including 2 Associates, 1 BD lead, and 1 in-house counsel. They maintain a cadence of 1 platform acquisition per year, noting it takes 12 months to fully stabilize a business post close. With $40m in total EBITDA across 4 current platforms, Corbin and Alex are approaching max capacity. One feature is that they prioritize high equity alignment, not only with a rolling seller (where applicable), but also with management teams who often access a 10% incentive pool.


Rise Run targets risk-averse founders who have stopped reinvesting in growth, to the chagrin of employees. This enables Alex and Corbin to "liberate" the employees with immediate post-closing impact. This may take the form of renting an Airbnb for 2 weeks to host workshops with every functional department, where they can whiteboard a 5-year roadmap based on raw feedback from employees previously stifled by old ownership. This not only uncovers ideas from the grass roots, but also provides instant cultural alignment between them as new owners and the team. The goal is to identify at least 2 major organic growth levers (or validating them, if found during the due diligence).
Corbin and Alex are active in daily operations, sometimes even serving as interim CFOs. They argue that sub-$5m EBITDA companies lack the cash flow to afford expensive consultants, which forces them as the sponsor to be the primary executor of the value creation plan. By keeping leverage low and staying in the $2-7m EBITDA box, they create a margin of safety.
Alex was previously a QoE provider, having completed 2,500 QoEs prior to starting Rise Run. So he can vet deals with extreme speed. This muscle memory allows Rise Run to ignore "pretty" brokered books and chase messy Word doc CIMs that others overlook. They often embark on 24-month courting periods with sellers to build trust and ensure a deal is "fully baked" before socializing it with equity investors. This proprietary persistence is deliberate, and once they followed up monthly for a full year with zero response before eventually hearing back and closing a winner.
More recent episodes
Funding Deal #2 From Exit #1
Ben Tiggelaar acquired Enable Dental in 2017, ran it for five years and exited in 2022. He later bought Datatel with his own capital, growing it from a $6m revenue MSP with 55–60% recurring revenue to ~$8m with ~90% recurring revenue.
Rolling Up Tiny $400k EBITDA Targets
Ziv Bendor co-founded Pinewell Capital in Scottsdale in 2016. Pinewell is now on its 5th platform and 10th acquisition across B2B and B2C businesses, including one strategy that combined four sub-$500k EBITDA companies into a ~$7m EBITDA platform.
Over $60m of Second Bite Liquidity
Chad Scripps started Black Lake Capital in 2013 after stints at McKinsey, HIG, and several hedge funds. Based in Denver, Black Lake closes just 1-2 acquisitions per year despite reviewing thousands of opportunities. The firm calls itself tech-enabled, but Chad admits that’s a loose moniker: “If you’ve got email, we’ll call you tech enabled.”