Financing Add-Ons Without New Equity
Sam Turner built Advantos Group into a leading UK facilities maintenance roll-up through disciplined capital management, technology integration, and conservative leverage below 2x EBITDA.


UK-based Sam Turner overcame a challenged first deal by pivoting the business model and eventually built a thriving facilities maintenance roll-up that targets market leadership in its space. He points to capital stack discipline as key when self-funding add-on acquisitions. Beyond work, Sam volunteers one full mentorship day per month to founders and prospective business buyers.
Sam Turner's Advantos Group aims to be the UK's favorite platform for independent mechanical, electrical, and facilities management companies. Sam owns ~70% of the equity following the initial acquisition in Dec 2021. He came from a multibillion corporate background and now applies that experience to acquire at 3-4x EBITDA.
Advantos's success relied on technology implementation and people development. Sam paused M&A for nearly a year to implement systems to avoid ten people doing ten different versions of the same process. He introduced structured sales pipelines and field management tools that replaced ad hoc spreadsheets. One strong senior hire transformed performance and created the foundation for yearly organic growth of 15%.
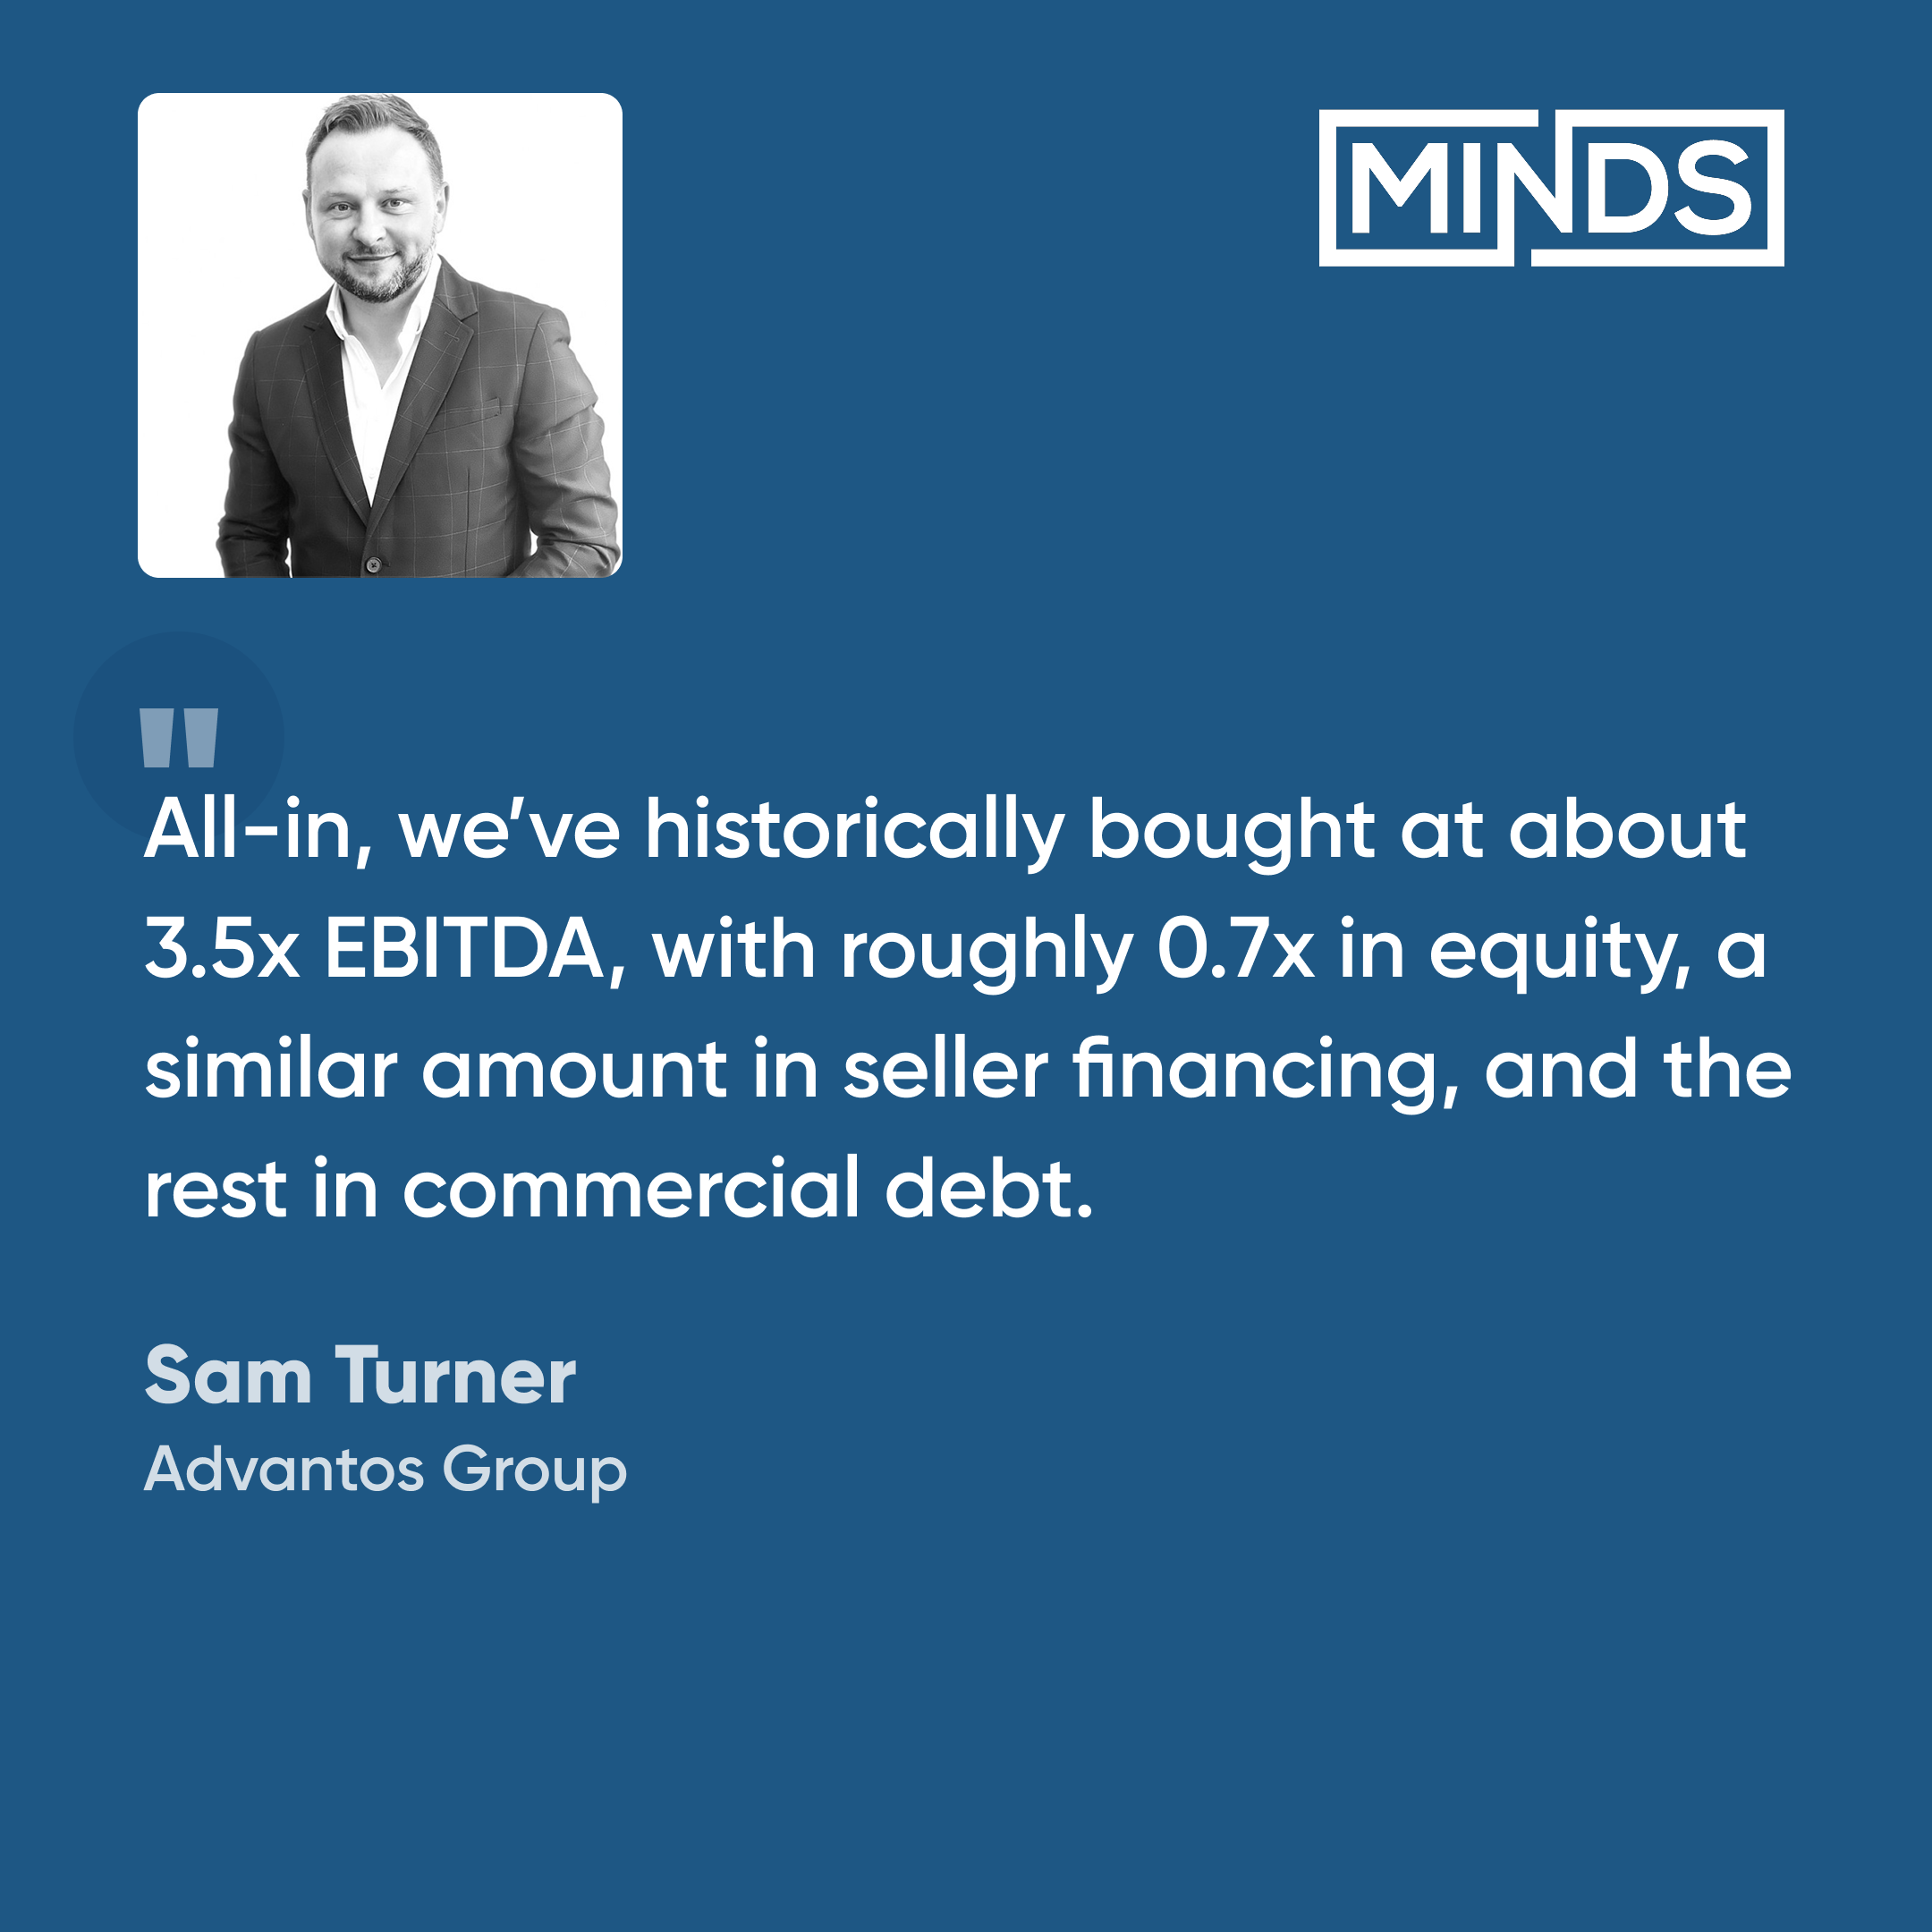
Sam advocates for conservative underwriting, where he prefers to keep net leverage at or below 2x EBITDA. He's capitalized his deals with 0.7x equity, 0.7x seller financing, and 2.2x of commercial debt. In December 2023 the group refinanced with a debt fund at ~11% on a 5-year term with about 8% cash pay and 3% PIK. Future acquisitions in the 4.0-4.5x EBITDA range can be done without new equity by using ~1.5x of surplus cash from the balance sheet, 2x of senior debt, and the remainder strategically coming from deferred consideration or earn-outs.
Sam's personal philosophy is to give away his time before he has excess money. He donates one full day each month to founders and searchers. He keeps his own salary low so capital stays inside the business where it can compound. For him the idea is simple: Act today. Help today. Build wealth and impact in parallel rather than in sequence.
More recent episodes
The $600M Bet on Independent Sponsors
Grant Kornman co-founded NCK Capital as an independent sponsor in 2013, then moved to the capital side with Align Collaborate in 2023. Align now manages $600m+ across 2 dedicated funds and writes $10-40m equity checks into sponsor-led LMM deals. Grant has watched the independent sponsor market evolve from both sides.
815 Independent Sponsor Deals Analyzed
Greg Brown is a Professor of Finance at UNC Kenan-Flagler and Founder of the Institute for Private Capital. On July 15, 2026, he published the first large-scale study of independent sponsor performance, covering 815 deals. Investor-reported transactions generated a 2.86x average gross TVPI and 29.3% gross IRR, outperforming matched non-IS PE deals by 0.73x TVPI and 11.4% IRR on average, with no statistically significant increase in downside risk.
When Equity Oversubscribes 2-3x
Sequoya Borgman is the first repeat guest on the Minds Capital Podcast. Since his last appearance, Borgman Capital has exited 1 company (4x+ net MOIC) and acquired 2 more (Minds Capital invested in the latest one, PCCD)